For most of your working life, receiving income is relatively simple. Your employer deposits a paycheck into your bank account every two weeks, and you use that income to pay bills, save, invest, and enjoy your life.
Retirement changes that process.
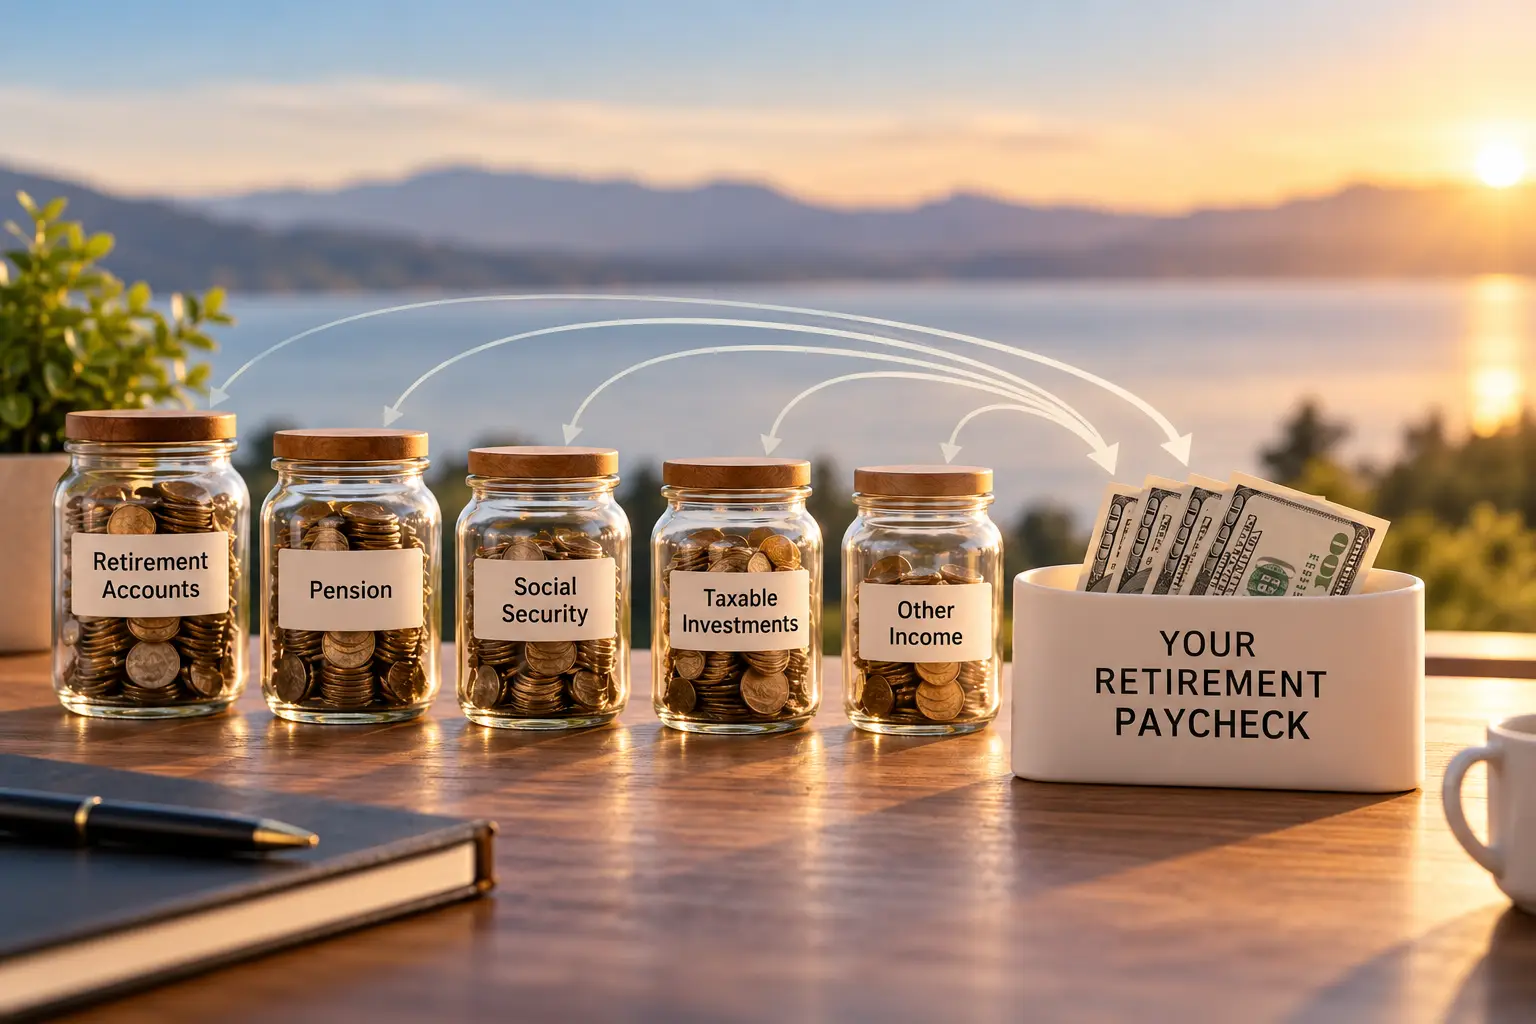
Instead of receiving a paycheck from an employer, you may need to create your own income stream from several sources. Those sources may include retirement accounts, pensions, Social Security, taxable investments, or part-time work.
The challenge is not simply saving enough. It is knowing how to turn those resources into a reliable retirement paycheck that can support your lifestyle. Before creating that paycheck, it helps to understand whether you have a retirement income gap between your expected income and spending.
Retirement Income Comes From Several Sources
Most retirees rely on a combination of income sources rather than a single account.
Retirement accounts. Accounts such as 401(k)s, 403(b)s, 457 plans, and IRAs may represent a significant portion of your retirement savings. Traditional retirement accounts generally provide tax-deferred growth, with withdrawals typically subject to income taxes. Roth accounts are funded with after-tax dollars, and qualified withdrawals may be tax-free.
But the account itself does not create a paycheck. You create the paycheck by deciding how much to withdraw, when to withdraw it, and which accounts to use.
Pensions. A defined benefit plan, commonly called a pension, may provide predetermined income based on factors such as salary history and years of service.
Retirees may have choices about how those benefits are received, including single-life or joint-and-survivor benefits. Some plans may also offer a lump-sum option. Each choice can create different tradeoffs involving income, flexibility, and protection for a surviving spouse.
Social Security. Social Security can provide an important foundation for a retirement paycheck. Your benefit is based in part on your earnings history and when you decide to claim it.
But the right claiming decision involves more than trying to maximize a monthly payment. Health, longevity, spousal benefits, taxes, cash-flow needs, and other retirement resources may all influence the decision.
Other Assets Can Provide Flexibility
Taxable brokerage accounts and Roth IRAs may provide additional flexibility when coordinating retirement income.
For example, selling investments from a taxable account can have different tax consequences than withdrawing money from a traditional retirement account. Roth IRAs may provide qualified tax-free withdrawals and can offer another source of flexibility later in retirement.
Each account has different tax characteristics.
The goal is not simply to withdraw money from whichever account has the highest balance. It is to coordinate your resources so they work together.
Turn Your Assets Into a Coordinated Paycheck
Once you know where your retirement income will come from, the next challenge is determining how those sources should work together.
A coordinated retirement income strategy considers questions such as:
- How much income will you need each month?
- When should Social Security begin?
- How should pension benefits fit into the plan?
- Which accounts should fund your spending?
- How might inflation affect future expenses?
- What happens to withdrawals during a market decline?
- How might required minimum distributions affect future income and taxes?
- How much flexibility should remain for unexpected expenses and legacy goals?
These decisions are interconnected. Changing when you claim Social Security, for example, may change how much you need to withdraw from your portfolio. Where those withdrawals come from may then affect your taxes.
That is why creating a retirement paycheck is more than establishing a monthly withdrawal.
Market Timing Matters When You Are Taking Income
One risk deserves particular attention: sequence-of-returns risk.
During your working years, a market decline may give your portfolio time to recover while you continue making contributions.
Retirement can be different.
If you are withdrawing from your portfolio during a prolonged market decline, you may be selling investments at lower values while simultaneously removing money needed for living expenses. That combination can make it more difficult for the portfolio to recover and support future withdrawals.
A thoughtful income plan cannot eliminate market risk or guarantee that your money will last. It can, however, prepare for different market environments and provide a framework for making withdrawals more intentionally.
Your Retirement Paycheck Should Evolve
Your income needs probably won’t remain unchanged for 30 years.
You may spend more on travel and activities during the early years of retirement. Healthcare expenses may become more significant later. Taxes, markets, housing, family needs, and your lifestyle can change along the way.
Your retirement income strategy should be able to change with them.
That means periodically revisiting your withdrawals, investment allocation, tax strategy, and other income decisions as your circumstances evolve.
From Savings to Income
Turning retirement savings into a paycheck requires more than dividing an account balance by the number of years you expect to live.
It requires coordination.
Your retirement assets are more than balances on a statement. Together with Social Security, pensions, and other resources, they can become the income that supports the next stage of your life.
The earlier you begin thinking about how those pieces will work together, the more time you have to identify potential gaps and make adjustments before your employment paycheck ends.